I spent time with Truist Mobile as a practical banking companion rather than treating it like another app to open once and forget. It is a free finance app from Truist Financial Corporation, designed for people who already use Truist banking services and want everyday account access from an Android phone. The overall impression is straightforward: it puts routine money tasks in one place, but its value depends heavily on whether Truist is your bank in the first place.
The app has been available since April 27, 2021, and supports Android 9 or later. That makes it accessible to many users with older phones, although banking apps should still be used on a device that receives current security updates. It is rated for Everyone, and its public reception is notably strong, with a 4.8 average from around 382 thousand ratings and more than 1 million installs. Those figures suggest that the basic experience works well for a large audience, but they should not be mistaken for a guarantee that every banking situation will feel equally smooth.
How Truist Mobile fits into everyday banking
A useful home base for routine money tasks
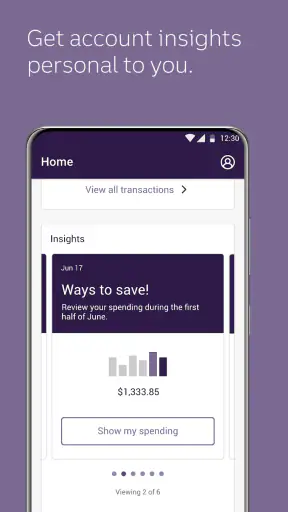
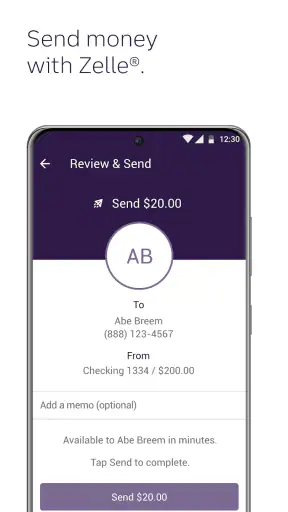
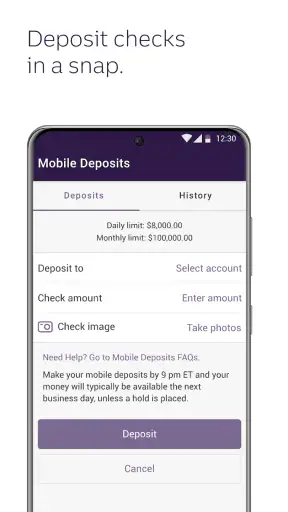
What I like most about a bank app is not flashy presentation; it is the ability to answer small financial questions quickly. How much is available? Did a payment go through? Is a deposit visible? Can I move money without opening a laptop? Truist Mobile is aimed at that kind of repeated use. It makes sense as a daily check-in point for customers who want their banking relationship close at hand.
In a realistic weekday scenario, I might use it before leaving for work to confirm that a paycheck or transfer has appeared, then check recent activity after buying groceries. Later, I could return to review whether a scheduled payment has been processed. That sequence sounds ordinary, but ordinary is exactly where a mobile banking app earns its place. The less effort required to verify basic account activity, the less likely I am to postpone it.
The app is also more useful when treated as a record-keeping tool rather than only an emergency wallet. Reviewing transactions regularly can help spot an unfamiliar charge while it is still easy to remember what happened. I would not wait until the end of the month to discover that my balance changed unexpectedly. A short, frequent check is more practical than a long financial cleanup session.
Who will get the most from it
Truist customers who manage their finances mainly from a phone are the natural audience. It should appeal to someone who wants a single mobile entry point for checking day-to-day activity, handling common banking actions, and staying aware of account movement without relying on a desktop browser.
It can also suit people who prefer a bank-specific experience over a separate budgeting service. A budgeting app may offer broader views across multiple institutions, but it introduces another login, another synchronization process, and another place to review sensitive information. If most of your financial life is already with Truist, using the bank’s own app keeps the routine closer to the source.
Families and couples should think more carefully about their workflow. The app may be convenient for the individual whose accounts are connected to Truist, but shared financial decisions still require clear communication. A mobile screen can show activity quickly; it does not automatically replace a household system for assigning bills, discussing spending, or tracking goals.
The first setup deserves patience
My advice is to avoid judging a banking app during the first few minutes. The important part of setup is not simply getting past the login screen. It is making sure the account list, alerts, and security choices fit the way you actually bank. If you rush through those steps, you may later find yourself checking the wrong account or missing useful notifications.
I would also begin with a quiet setup session rather than trying to register while standing in a checkout line. Keep your phone’s operating system current, use a strong device lock, and avoid signing in over an unfamiliar public network. These are not exciting features, but they matter more for a finance app than decorative design does.
What the app does better than a browser
A mobile banking app earns its place by reducing friction compared with a browser. A dedicated app is already shaped for a smaller screen, and it is easier to reach when I need to check something immediately. That matters when I am confirming a payment at a store, reviewing a transfer before it becomes a problem, or checking whether a deposit has arrived.
The browser remains useful for longer sessions, especially when I want to compare many transactions or work through a complicated financial task. A desktop display gives more room for reading and organizing information. My preferred approach is not to treat the app and website as rivals: I use the phone for quick awareness and the larger screen when the task requires concentration.
Where it sits beside other finance apps
Compared with a general-purpose money manager, Truist Mobile has one major advantage: it is tied directly to the bank relationship rather than trying to assemble a picture from several institutions. That can make routine account checking feel more immediate. The trade-off is scope. A dedicated bank app is not automatically the best place for a complete household budget, investment comparison, debt plan, or cross-bank overview.
Compared with a digital-only banking service, the appeal is different again. A bank-specific app is valuable when the user wants continuity with an existing Truist account. Someone choosing a financial provider primarily for a minimalist mobile experience may prefer to compare the entire banking relationship, not just the application. An attractive interface cannot compensate for fees, account terms, branch needs, or service preferences that do not match the user.
What has changed, what still matters, and what I would watch
The product’s established direction
Because the app arrived in 2021, it is not a brand-new experiment. Its development has had time to move beyond the question of whether a bank should offer mobile access at all. The more relevant question now is how consistently the experience supports real banking habits: quick checks, clear account information, dependable transactions, and sensible security.
I see that as an important distinction. A finance app does not need constant visual reinvention to be useful. In fact, frequent changes to navigation can irritate people who only want to find the same account or activity screen they used yesterday. The strongest evolution for this type of product is often quiet: fewer confusing steps, clearer status information, and better handling of the moments when something needs attention.
The public response gives the app a strong starting point. An average of 4.8 and roughly 40 thousand written reviews indicate that many users are satisfied enough to rate or discuss the experience. Still, ratings compress many different situations into one number. A person who only checks balances may be delighted, while another who needs a complicated transfer or has an account-specific issue may evaluate the app much more critically.
How existing users should approach updates
For someone already using Truist Mobile, I would pay attention to changes in navigation before assuming an update is merely cosmetic. Banking workflows depend on muscle memory. After an update, take a moment to locate the screens you use most, verify that your preferred alerts are still configured, and check that the correct accounts appear where expected.
I would also avoid performing an important financial action immediately after a major app change unless there is time to review the confirmation carefully. That is not a criticism of Truist Mobile specifically; it is sensible behavior whenever a familiar interface moves buttons, labels, or confirmation steps. A few extra seconds spent reading the final screen is worthwhile when money is involved.
Existing users should keep another habit: distinguish between a displayed balance and the money they can comfortably spend. Pending activity, scheduled payments, and recent purchases can affect the practical amount available even when the headline number looks reassuring. The app can help you observe account activity, but responsible decisions still require reading the transaction details and remembering commitments outside the screen.
Three less obvious ways to use it well
First, I would use the app as a short daily audit rather than only opening it when something goes wrong. Reviewing the newest activity while each purchase is still fresh makes unfamiliar transactions easier to recognize. It also creates a simple personal rhythm: check, understand, and move on, instead of allowing several weeks of activity to pile up.
Second, I would separate “checking information” from “taking action.” When I am tired or distracted, I might open the app only to confirm a balance and leave transfers or payments for a calmer moment. That small distinction reduces the chance of selecting the wrong account or entering an amount too quickly. Convenience is helpful, but financial convenience should not become careless speed.
Third, I would use a larger screen for planning and Truist Mobile for follow-through. For example, I might review a monthly budget on a computer, then use the phone during the week to verify that actual transactions match the plan. This division plays to the strengths of each format and avoids forcing a small display to handle work that is easier to understand with more space.
A fourth useful habit is to treat notifications as prompts to investigate, not as complete explanations. An alert can tell me that something happened, but I still need to open the relevant activity and confirm the details. That is particularly important when several transactions occur close together or when a payment’s status changes over time.
Remaining friction and who should skip it
The biggest limitation is structural: Truist Mobile is most compelling for Truist customers. If your accounts are spread across several banks, the app will not replace a service built around an all-in-one financial overview. You may still need another tool to see the complete picture, and switching between apps can undermine the simplicity you wanted.
I would also skip it as a primary solution if your main goal is advanced budgeting, detailed spending analysis, or financial planning across institutions. A bank app can be excellent at showing the bank’s side of your money without being a full personal-finance command center. Choosing the right category matters more than choosing the highest-rated individual app.
Users who rarely bank by phone may not gain much from installing it. If you prefer visiting a branch, calling support, or using a desktop for every task, the mobile convenience may not justify changing your routine. The app is strongest when quick access genuinely changes how often you check and manage your finances.
There is also a human limitation that no interface removes: mobile screens encourage fast decisions. If you are making a large payment, moving money between accounts, or investigating an unfamiliar transaction, slow down. Read the account name, amount, and confirmation information instead of relying on a quick tap. The app can make banking more accessible, but it cannot make an incorrect selection harmless.
Questions I would answer before installing
If you are wondering whether it costs anything to download, Truist Mobile is free. That describes the app itself, not every possible cost associated with a bank account or banking service. I would still review the terms connected to the specific account and transaction before assuming that mobile access changes those conditions.
If you are asking whether an older Android phone can run it, the stated minimum is Android 9. Compatibility is only one part of the decision, though. A phone that technically meets the requirement but no longer receives security updates is not my preferred device for financial activity. I would use a supported, protected phone and keep the app current.
If you are deciding between the app and online banking, I would choose based on the task. The app is better for quick checks while away from a desk. A browser can be more comfortable for extended review, especially when I need to read many entries or think through a broader financial plan. Having both options is more useful than insisting that one should replace the other.
If you are concerned about whether it is suitable for a child, its content rating is Everyone, but that is not the same as saying every banking feature is appropriate for every age. Banking access should be based on the account holder, legal permissions, and family supervision. The rating describes the app’s general content, not a recommendation to give financial access without oversight.
Finally, if you are asking whether the strong rating means it will solve every banking problem, my answer is no. It is a positive signal about broad user satisfaction, not a substitute for checking whether Truist supports the accounts and habits you personally rely on. I would install it when the bank relationship is already right and the mobile workflow is the missing convenience.
What I would like to see next
Future development should focus on clarity during important moments. I would watch for improvements that make transaction status, account selection, and confirmation steps easier to understand without adding visual clutter. In finance, a calm and unambiguous screen is more valuable than a clever animation or a constantly changing layout.
I would also pay attention to how the app handles the balance between speed and caution. The best experience lets me complete a simple check quickly while giving me enough context before an action with consequences. That balance is difficult: too many confirmations make routine banking tiresome, but too little information encourages mistakes.
Another area worth watching is how well the app serves customers whose financial lives are becoming more complex. A person may begin with one account and later add shared expenses, recurring obligations, or accounts at other institutions. Truist Mobile does not need to become every kind of finance tool, but it should remain clear about where it is strongest and make its core banking workflows dependable as users grow.
My recommendation
After looking at the app as a daily banking tool, I would recommend Truist Mobile to Truist customers who want dependable mobile access for routine account awareness and actions. Its free price, broad Android compatibility, and strong user reception make it an easy app to consider when the bank relationship is already in place. The most convincing benefit is not a single flashy feature; it is the ability to keep ordinary money checks close by.
I would be more cautious for someone searching for a complete budgeting platform or a way to combine every financial account in one dashboard. In that case, a dedicated personal-finance service may be a better companion, while Truist Mobile remains the authoritative place to inspect Truist activity. That combination can be more realistic than expecting one app to handle every financial need.
My bottom line is simple: choose Truist Mobile for convenient access to your Truist banking relationship, not as a universal replacement for every finance tool. Used with careful review of balances, transactions, and confirmations, it can become a sensible part of a regular money routine. Just keep expectations tied to its role as a bank app, and use a browser or a broader budgeting tool when the job demands more space or a wider view.


